

GARCHProcess
GARCHProcess[κ,{α1,…,αq},{β1,…,βp}]
標準ホワイトノイズで駆動される,次数 p および q のGARCH(一般化された自己回帰条件付き分散不均一)過程を表す.
GARCHProcess[κ,{α1,…,αq},{β1,…,βp},init]
初期データが init であるGARCH過程を表す.
詳細
- GARCHProcessは,離散時間・連続状態のランダム過程である.
- 条件付き平均Expectation[x[t]{x[t-1],…}]=0およびExpectation[x[t]2{x[t-1],…}]で与えられる条件付き分散
 が方程式
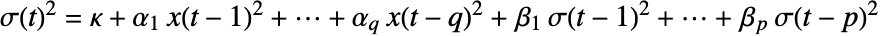 を満足するのであれば,過程 x[t]はGARCH過程である.
- 初期データinit はリスト{…,y[-2],y[-1]}として,またはタイムスタンプが{…,-2,-1}であると了解される単一路TemporalDataオブジェクトとして与えることができる.
- スカラーGARCHProcessは非負の係数 αi および βj,また正の係数 κ を持たなければならない.
- GARCHProcess[q,p]は,EstimatedProcessおよび関連関数で使われる,次数 q および p のGARCH過程を表す.
- GARCHProcessは,RandomFunction,CovarianceFunction,TimeSeriesForecast等の関数で使うことができる.
例題
すべて開く すべて閉じる例 (3)
GARCHProcessのシミュレーションを行う:
RandomFunction[GARCHProcess[2, {.1}, {.2}], {0, 10}]%["Path"]ListPlot[RandomFunction[GARCHProcess[2, {.1}, {.2}], {0, 100}], Filling -> Axis]Mean[GARCHProcess[κ, {Subscript[α, 1], Subscript[α, 2]}, {Subscript[β, 1], Subscript[β, 2], Subscript[β, 3]}][t]]Variance[GARCHProcess[κ, {Subscript[α, 1], Subscript[α, 2]}, {Subscript[β, 1], Subscript[β, 2], Subscript[β, 3]}][t]]Mean[GARCHProcess[1, {1 / 3}, {1 / 4}, {Subscript[x, -1]}][t]]Variance[GARCHProcess[1, {1 / 3}, {1 / 4}, {Subscript[x, -1]}][t]]data = RandomFunction[GARCHProcess[1, {.1, .3}, {.2}], {10 ^ 3}];
corr = CorrelationFunction[data, {20}];ListPlot[corr, Filling -> Axis, PlotRange -> All]corr2 = CorrelationFunction[data ^ 2, {20}];ListPlot[corr2, Filling -> Axis, PlotRange -> All]スコープ (13)
基本的な用法 (8)
data = RandomFunction[GARCHProcess[.3, {.5}, {.2}], {0, 30}, 4]ListLinePlot[data, Filling -> Axis]RandomFunction[GARCHProcess[1 / 3, {1 / 10}, {1 / 4}], {5}, WorkingPrecision -> 20]["Path"]sproc[x_] := GARCHProcess[.03, {.4}, {.3}, {x}];pts = {-1, 0, 2};samples = Table[SeedRandom[4];RandomFunction[sproc[x], {20}], {x, pts}];ListLinePlot[samples, DataRange -> {0, 12}, PlotLegends -> (StringJoin["x = ", ToString[#]]& /@ pts)]tproc[x_] := GARCHProcess[.03, {.7}, {.8}, {x}];tsamples = Table[SeedRandom[4];RandomFunction[tproc[x], {20}], {x, pts}];ListLinePlot[tsamples, DataRange -> {0, 12}, PlotRange -> All, PlotLegends -> (StringJoin["x = ", ToString[#]]& /@ pts)]積分されたGARCHProcess:
α = .4;
proc = GARCHProcess[1, {α}, {1 - α}, {}];ListPlot[RandomFunction[proc, {0, 100}], Filling -> Axis]爆発GARCHProcess:
proc = GARCHProcess[2, {.3, .7}, {.4, .2}, {}];ListPlot[RandomFunction[proc, {0, 100}], Filling -> Axis]WeakStationarity[proc]GARCHProcessが共分散定常になるための条件:
WeakStationarity[GARCHProcess[κ, {Subscript[α, 1], Subscript[α, 2]}, {Subscript[β, 1], Subscript[β, 2]}]]GARCHProcess[1,1]の二次定常性の範囲:
cond = WeakStationarity[GARCHProcess[κ, {α}, {β}]]RegionPlot[cond, {α, 0, 1}, {β, 0, 1}, FrameLabel -> Automatic]GARCHProcessを推定する:
SeedRandom[34];
data = RandomFunction[GARCHProcess[.3, {.2}, {.4}], {6 10 ^ 2}];tsm = TimeSeriesModelFit[data, {"GARCH", {1, 1}}]tsm["Process"]EstimatedProcess[data, GARCHProcess[1, 1], ProcessEstimator -> "MaximumConditionalLikelihood"]proc = GARCHProcess[.3, {.5}, {.4}];
data = RandomFunction[proc, {10 ^ 2}];forecast = TimeSeriesForecast[proc, data, {20}];forecast["Path"]errors = forecast["MeanSquaredErrors"]予測状態は0に等しい.従って,予測される標準偏差境界は以下の通りである:
ubound = TimeSeriesMap[Sqrt, errors];
lbound = TimeSeriesMap[-Sqrt[#]&, errors];ListLinePlot[{data, forecast, lbound, ubound}, PlotStyle -> {Automatic, Automatic, Red, Red}, Filling -> {3 -> {4}}]過程スライス特性 (5)

proc = GARCHProcess[k, {α}, {β}];Moment[proc[t], 4]//SimplifyCumulant[proc[2], 4]DiscretePlot[Moment[GARCHProcess[1, {.4}, {.1}, {}][t], 4], {t, 0, 4}]Moment[GARCHProcess[.06, {0.5}, {.3}, {}][2], 4]Cumulant[GARCHProcess[.3, {.1, .4}, {.2}, {}][2], 4]Skewness[GARCHProcess[κ, {α}, {β}][t]]Skewness[GARCHProcess[κ, {α}, {β}, {x}][t]]Kurtosis[GARCHProcess[κ, {α}, {β}][t]]RegionPlot[Not[β ≤ 0 || 105 α^4 + 60 α^3 β + 18 α^2 β^2 + 4 α β^3 + β^4 ≥ 1], {α, 0, 1}, {β, 0, 1}, FrameLabel -> Automatic]proc[α_] := GARCHProcess[.3, {α}, {.2}];
sample[α_] := RandomVariate[proc[α][3], 10 ^ 4];r = {.1, .3, .5, .7};Histogram[sample[#], Automatic, "PDF", PlotLabel -> StringJoin["α = ", ToString[#]]]& /@ rモンテカルロ法を使い,スライス分布についてのNProbabilityを計算する:
proc = GARCHProcess[1, {.3}, {.2}];NProbability[x[1] > .3, xproc, Method -> {"MonteCarlo", "SamplingIncrement" -> 10 ^ 4}]NExpectationを計算する:
NExpectation[x[2] ^ 2, xproc, Method -> {"MonteCarlo", "SamplingIncrement" -> 10 ^ 4}]2次’Momentと比較する:
Moment[proc[2], 2]特性と関係 (3)
GARCHProcessの値は無相関である:
Correlation[GARCHProcess[2, {.3, .2}, {.2, .1}][{1, 2, 3}]]//MatrixForm対応するARMAProcess:
ARMAProcess[GARCHProcess[2, {.3}, {.1}]]ARMAProcess[GARCHProcess[2, {.3}, {.1}, {3, 2}]]GARCHProcessの値を平方したものはARMAProcessに従う:
proc = GARCHProcess[1, {.2, .3}, {.4}];data = RandomFunction[proc, {10 ^ 6}];平方値のCorrelationFunctionおよびPartialCorrelationFunction:
dataSQ = data ^ 2;
ListPlot[#[dataSQ, {1, 30}], Filling -> Axis, PlotRange -> {-.2, 1}, PlotLabel -> #]& /@ {CorrelationFunction, PartialCorrelationFunction}arma = ARMAProcess[proc]ARMA過程のCorrelationFunctionおよびPartialCorrelationFunction:
ListPlot[#[arma, {1, 30}], Filling -> Axis, PlotRange -> {-.2, 1}, PlotLabel -> #]& /@ {CorrelationFunction, PartialCorrelationFunction}テキスト
Wolfram Research (2014), GARCHProcess, Wolfram言語関数, https://reference.wolfram.com/language/ref/GARCHProcess.html.
CMS
Wolfram Language. 2014. "GARCHProcess." Wolfram Language & System Documentation Center. Wolfram Research. https://reference.wolfram.com/language/ref/GARCHProcess.html.
APA
Wolfram Language. (2014). GARCHProcess. Wolfram Language & System Documentation Center. Retrieved from https://reference.wolfram.com/language/ref/GARCHProcess.html