GARCHProcess
GARCHProcess[κ,{α1,…,αq},{β1,…,βp}]
表示阶数为 p 和 q,通过标准白噪声驱动的广义自回归条件异方差过程.
GARCHProcess[κ,{α1,…,αq},{β1,…,βp},init]
表示初始数据为 init 的 GARCH 过程.
更多信息
- GARCHProcess 是一个离散时间和连续状态的随机过程.
- 过程 x[t] 是一个 GARCH 过程,若条件均值 Expectation[x[t]{x[t-1],…}]=0 且由 Expectation[x[t]2{x[t-1],…}] 给出的条件方差
 满足方程
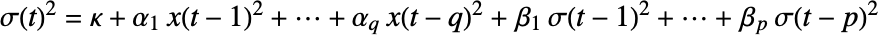 .
- 初始数据 init 可以用列表 {…,y[-2],y[-1]} 或时间戳为 {…,-2,-1} 的单一路径 TemporalData 对象的形式给出.
- 标量 GARCHProcess 应该具有非负系数 αi 和 βj 以及正系数 κ.
- GARCHProcess[q,p] 表示阶数 q 和 p 的 GARCH 过程,以用于 EstimatedProcess 及相关函数.
- GARCHProcess 可以与诸如 RandomFunction、CovarianceFunction 和 TimeSeriesForecast 等函数结合使用.
范例
打开所有单元 关闭所有单元基本范例 (3)
模拟 GARCHProcess:
RandomFunction[GARCHProcess[2, {.1}, {.2}], {0, 10}]%["Path"]ListPlot[RandomFunction[GARCHProcess[2, {.1}, {.2}], {0, 100}], Filling -> Axis]Mean[GARCHProcess[κ, {Subscript[α, 1], Subscript[α, 2]}, {Subscript[β, 1], Subscript[β, 2], Subscript[β, 3]}][t]]Variance[GARCHProcess[κ, {Subscript[α, 1], Subscript[α, 2]}, {Subscript[β, 1], Subscript[β, 2], Subscript[β, 3]}][t]]Mean[GARCHProcess[1, {1 / 3}, {1 / 4}, {Subscript[x, -1]}][t]]Variance[GARCHProcess[1, {1 / 3}, {1 / 4}, {Subscript[x, -1]}][t]]data = RandomFunction[GARCHProcess[1, {.1, .3}, {.2}], {10 ^ 3}];
corr = CorrelationFunction[data, {20}];ListPlot[corr, Filling -> Axis, PlotRange -> All]corr2 = CorrelationFunction[data ^ 2, {20}];ListPlot[corr2, Filling -> Axis, PlotRange -> All]范围 (13)
基本用法 (8)
data = RandomFunction[GARCHProcess[.3, {.5}, {.2}], {0, 30}, 4]ListLinePlot[data, Filling -> Axis]RandomFunction[GARCHProcess[1 / 3, {1 / 10}, {1 / 4}], {5}, WorkingPrecision -> 20]["Path"]sproc[x_] := GARCHProcess[.03, {.4}, {.3}, {x}];pts = {-1, 0, 2};samples = Table[SeedRandom[4];RandomFunction[sproc[x], {20}], {x, pts}];ListLinePlot[samples, DataRange -> {0, 12}, PlotLegends -> (StringJoin["x = ", ToString[#]]& /@ pts)]tproc[x_] := GARCHProcess[.03, {.7}, {.8}, {x}];tsamples = Table[SeedRandom[4];RandomFunction[tproc[x], {20}], {x, pts}];ListLinePlot[tsamples, DataRange -> {0, 12}, PlotRange -> All, PlotLegends -> (StringJoin["x = ", ToString[#]]& /@ pts)]一个集成的 GARCHProcess:
α = .4;
proc = GARCHProcess[1, {α}, {1 - α}, {}];ListPlot[RandomFunction[proc, {0, 100}], Filling -> Axis]发散的 GARCHProcess:
proc = GARCHProcess[2, {.3, .7}, {.4, .2}, {}];ListPlot[RandomFunction[proc, {0, 100}], Filling -> Axis]WeakStationarity[proc]GARCHProcess 成为协方差平稳过程的条件:
WeakStationarity[GARCHProcess[κ, {Subscript[α, 1], Subscript[α, 2]}, {Subscript[β, 1], Subscript[β, 2]}]]GARCHProcess[1,1] 具有二阶平稳性的区域:
cond = WeakStationarity[GARCHProcess[κ, {α}, {β}]]RegionPlot[cond, {α, 0, 1}, {β, 0, 1}, FrameLabel -> Automatic]估计 GARCHProcess:
SeedRandom[34];
data = RandomFunction[GARCHProcess[.3, {.2}, {.4}], {6 10 ^ 2}];tsm = TimeSeriesModelFit[data, {"GARCH", {1, 1}}]tsm["Process"]EstimatedProcess[data, GARCHProcess[1, 1], ProcessEstimator -> "MaximumConditionalLikelihood"]proc = GARCHProcess[.3, {.5}, {.4}];
data = RandomFunction[proc, {10 ^ 2}];forecast = TimeSeriesForecast[proc, data, {20}];forecast["Path"]errors = forecast["MeanSquaredErrors"]ubound = TimeSeriesMap[Sqrt, errors];
lbound = TimeSeriesMap[-Sqrt[#]&, errors];ListLinePlot[{data, forecast, lbound, ubound}, PlotStyle -> {Automatic, Automatic, Red, Red}, Filling -> {3 -> {4}}]过程切片性质 (5)

proc = GARCHProcess[k, {α}, {β}];Moment[proc[t], 4]//SimplifyCumulant[proc[2], 4]DiscretePlot[Moment[GARCHProcess[1, {.4}, {.1}, {}][t], 4], {t, 0, 4}]Moment[GARCHProcess[.06, {0.5}, {.3}, {}][2], 4]Cumulant[GARCHProcess[.3, {.1, .4}, {.2}, {}][2], 4]Skewness[GARCHProcess[κ, {α}, {β}][t]]Skewness[GARCHProcess[κ, {α}, {β}, {x}][t]]Kurtosis[GARCHProcess[κ, {α}, {β}][t]]RegionPlot[Not[β ≤ 0 || 105 α^4 + 60 α^3 β + 18 α^2 β^2 + 4 α β^3 + β^4 ≥ 1], {α, 0, 1}, {β, 0, 1}, FrameLabel -> Automatic]proc[α_] := GARCHProcess[.3, {α}, {.2}];
sample[α_] := RandomVariate[proc[α][3], 10 ^ 4];r = {.1, .3, .5, .7};Histogram[sample[#], Automatic, "PDF", PlotLabel -> StringJoin["α = ", ToString[#]]]& /@ r用蒙特卡罗方法计算切片分布的 NProbability:
proc = GARCHProcess[1, {.3}, {.2}];NProbability[x[1] > .3, xproc, Method -> {"MonteCarlo", "SamplingIncrement" -> 10 ^ 4}]计算 NExpectation:
NExpectation[x[2] ^ 2, xproc, Method -> {"MonteCarlo", "SamplingIncrement" -> 10 ^ 4}]与二阶 Moment 比较:
Moment[proc[2], 2]属性和关系 (3)
GARCHProcess 的值是互不相关的:
Correlation[GARCHProcess[2, {.3, .2}, {.2, .1}][{1, 2, 3}]]//MatrixForm对应的 ARMAProcess:
ARMAProcess[GARCHProcess[2, {.3}, {.1}]]ARMAProcess[GARCHProcess[2, {.3}, {.1}, {3, 2}]]GARCHProcess 的平方值服从 ARMAProcess:
proc = GARCHProcess[1, {.2, .3}, {.4}];data = RandomFunction[proc, {10 ^ 6}];平方值的 CorrelationFunction 和 PartialCorrelationFunction:
dataSQ = data ^ 2;
ListPlot[#[dataSQ, {1, 30}], Filling -> Axis, PlotRange -> {-.2, 1}, PlotLabel -> #]& /@ {CorrelationFunction, PartialCorrelationFunction}arma = ARMAProcess[proc]ARMA 过程的 CorrelationFunction 和 PartialCorrelationFunction:
ListPlot[#[arma, {1, 30}], Filling -> Axis, PlotRange -> {-.2, 1}, PlotLabel -> #]& /@ {CorrelationFunction, PartialCorrelationFunction}文本
Wolfram Research (2014),GARCHProcess,Wolfram 语言函数,https://reference.wolfram.com/language/ref/GARCHProcess.html.
CMS
Wolfram 语言. 2014. "GARCHProcess." Wolfram 语言与系统参考资料中心. Wolfram Research. https://reference.wolfram.com/language/ref/GARCHProcess.html.
APA
Wolfram 语言. (2014). GARCHProcess. Wolfram 语言与系统参考资料中心. 追溯自 https://reference.wolfram.com/language/ref/GARCHProcess.html 年